Tom Hartley Jnr does not operate a car dealership in any conventional sense. He runs a luxury automotive enterprise that functions, in financial terms, more like a specialised alternative-asset fund than a conventional dealership. While internet speculation churns out fabricated “net worth” figures with no basis in verified filings, the forensic reality is far more compelling: Hartley Jnr’s personal wealth is inextricably tied to the balance sheet of Tom Hartley Jnr Limited (Company number 06712857), a corporate entity that has grown from family-business offshoot to standalone enterprise generating £173 million in annual turnover.
The most recent Companies House filings reveal a business generating £173.29 million in direct turnover (year to March 2025), with pre-tax profits surging to £32.33 million—almost 3.5x the previous year’s £7.31 million. This is not a commission broker skimming percentages; this is a capital deployment machine that purchases, holds, and monetises hyper-rare automotive assets by deploying its own capital at risk — a model more commonly associated with fine-art dealers or private equity funds than with car dealerships.
What separates Hartley Jnr from every other operator in the ultra-luxury car ecosystem is the velocity of his capital and the depth of his market-making authority. While traditional dealerships scale via physical site volume, Hartley Jnr operates on a principal-trading model — acquiring hypercars outright as alternative investments rather than brokering them on consignment. His enterprise famously brokered the private treaty sale of Bernie Ecclestone’s historic collection of 69 Grand Prix and Formula 1 cars to Red Bull heir Mark Mateschitz, while subsequently brokering the Mansour Ojjeh McLaren collection of 20 McLaren road cars to a single anonymous buyer — a deal reported by Car Dealer Magazine at an eight-figure sum, which will contribute to FY2026 accounts.
“By several multiples the biggest sale price ever achieved for a classic car collection.”
— Tom Hartley Jnr, speaking to Telegraph Sport, March 2025
These are not transactions that happen through advertising or showroom footfall. They happen because Hartley Jnr has spent over 25 years building a network of trust, pricing intelligence, and deal-closing relationships that competitors cannot replicate that converts market knowledge into trading margins of up to 18.5% — significantly above the industry norm for brokered transactions.
Corporate Asset Audit: Tom Hartley Jnr Ltd
Balance Sheet Breakdown: Decoding the £72M Inventory and Companies House Filings
The financial architecture of Tom Hartley Jnr Limited, as disclosed in annual accounts filed at Companies House, reveals a capital structure that bears no resemblance to a standard automotive retail operation. For the period ending 31 March 2023, the company reported turnover of £181 million, pre-tax profit of £20.16 million, and gross profit margin of 13.5%—all from the sale of just 77 vehicles. The balance sheet showed £72 million tied up in physical stock and £32 million in cash reserves, creating enabling the company to purchase multi-million pound assets outright without waiting for bank credit approval.
The 2025 filing (year to March 2025) shows significant growth: turnover reached £173.29 million, pre-tax profit hit £32.33 million, and total assets stood at £87.78 million including cash reserves of £32.59 million. Vehicle sales volume increased from 81 to 105 units, with gross profit margin expanding to 18.5%—a significant jump from the 12% recorded in the prior year. The company paid £7 million in ordinary dividends during this period, with directors’ remuneration for qualifying services at a modest £12,576, underscoring that Hartley Jnr’s personal wealth extraction is primarily channelled through shareholder distributions rather than inflated salary structures.
What elevates this balance sheet above standard Tom Hartley Jnr financial accounts analysis is the composition of risk. The £72 million physical stock allocation represents not depreciating inventory but appreciating alternative assets—vehicles like the 1962 Ferrari 250 GTO, 1965 Ferrari 275 GTB, 1959 Ferrari 250 GT LWB California Spyder Competizione, Ferrari F40, McLaren P1, and Porsche 918 Spyder. In the ultra-luxury asset liquidity ecosystem, these are not products but stores of value that appreciate inversely to traditional automotive depreciation curves. The £32 million cash buffer provides immediate purchasing liquidity, enabling Hartley Jnr to execute on opportunities before competitors can arrange financing—a critical advantage when a single Ferrari 250 GTO can transact for prices approaching £41 million, as demonstrated by recent RM Sotheby’s auction results.
The Companies House Tom Hartley Jnr registry confirms zero charges or mortgages against the company—meaning no bank debt, no asset-backed lending, no leveraged inventory positions. This is pure equity-funded capital deployment. For a private supercar dealer valuation context, this unleveraged structure is virtually unprecedented in automotive retail and places Hartley Jnr’s enterprise in the same risk-bearing category as family offices and private equity funds specialising in tangible alternative assets.
The Self-Own Inventory Strategy: Why Bearing Full Market Risk Drives 18.5% Margins
The central thesis of Hartley Jnr’s business model is captured in his official filing text hosted on the Companies House Registry: “The business model is very different to most competitors due to the fact that the company aims to buy most of its inventory, compared to just brokering cars like many others who operate at this end of the market. This enables Tom Hartley Jnr Limited to potentially earn a greater gross margin as they bear the full risk, however due to this inherent risk element the director’s market knowledge on the particular cars and gut feeling of the market is very important.”
This is the essence of alternative asset risk deployment. Where commission brokers earn 5–10% on consignment sales with zero capital at risk, Hartley Jnr deploys corporate cash to outright purchase vehicles, capturing the full spread between acquisition and disposal.
By purchasing physical stock outright rather than relying on standard consignment, the firm converts proprietary pricing intelligence directly into its expanding 18.5% gross profit margins.
The mechanics are straightforward in theory but extraordinarily difficult in execution. Hartley Jnr identifies undervalued or fairly priced hyper-rare assets—often through private networks rather than public listings—deploys corporate capital for outright purchase, holds the asset while preparing it to museum-standard presentation, and then sells to a global clientele of UHNW collectors, sovereign wealth representatives, and institutional buyers. The luxury car dealer profit margins are not generated through volume but through precision: 77 vehicles generating £181 million in turnover means an average transaction value of approximately £2.35 million per unit. By 2025, 105 vehicles generated £173.29 million, maintaining a high-tier baseline value per transaction—though this figure reflects a blended balance of owned stock and strategic commission-based off-market brokerage.
The risk-bearing element cannot be overstated. When Hartley Jnr purchases a Ferrari 250 GTO or McLaren F1 for corporate inventory, he is not buying a depreciating consumer good. He is acquiring a concentrated position in an illiquid alternative asset class where price discovery is opaque and transaction windows can extend for months or years. A misjudged acquisition could tie up millions in capital with no exit path. The Tom Hartley Jnr business revenue figures demonstrate that this risk is not merely managed but mastered—converted into a sustainable competitive advantage that competitors cannot replicate without both the capital base and the decades of market-specific expertise required to price these assets accurately.
The Evolution of an 11-Year-Old Prodigy: Tracking the Legacy Capital Buffer
Tom Hartley Jnr’s wealth trajectory is not a story of inherited privilege but of accelerated capital compounding that began in childhood. Born in July 1983, he left formal schooling at age 11 to work in his father’s Derbyshire-based luxury car dealership—an “early apprenticeship” that provided immersion in the mechanics of high-value transactions before most children have completed secondary education. As he told Regtransfers: “I left school at 11 years old to work in my father’s car business. This was, maybe, an early apprenticeship but the best foundation I could have ever asked for.” By age 16, he held a 50% share in the family business, having spent five years absorbing the pricing dynamics, client relationships, and negotiation skills that define the upper echelons of the collector car market.
The critical inflection point came in 2014, when Hartley Jnr formally separated from the family firm. Tom Hartley Jnr Ltd had been incorporated back in October 2008, but it took full operational shape as a standalone trading entity under his sole leadership from 2014 onwards, initially headquartered in Ashby-de-la-Zouch, Leicestershire, near the Derbyshire border — before relocating to a purpose-built facility in Hook Norton, Oxfordshire, which officially opened on 29 June 2026. This was not a hostile split—his father tweeted support with the hashtag #unique&amazingbusinessman—but a strategic divergence based on Hartley Jnr’s conviction that the future of ultra-luxury automotive trading lay not in volume retail but in hyper-focused curation of the world’s most significant vehicles.
The compounding effect of this 25+ year transaction history is visible in the 2026 valuation framework. From a 2016 turnover already in excess of £100 million — just two years after the independent venture launched — the business has scaled to £173.29 million in direct turnover plus off-market commission volumes that push total concluded transactions well above £200 million annually. The Queen’s Award for Enterprise (International Trade) received in 2018 validated this trajectory, citing overseas turnover growth from £14.5 million to £33.3 million between 2014 and 2018 — a 130% increase, as cited on the company’s own website that established global market-making authority before the business reached its current scale.
Hartley Jnr reportedly became Britain’s youngest self-made millionaire at 15, according to the Derbyshire Times — though this was achieved while working within the family firm, not through an independent venture. His millionaire status was built not through a single liquidity event but through continuous reinvestment of trading profits into ever-larger inventory positions. By his own account, Hartley Jnr held a 50% share in the family business by age 16 — a pattern of early capital accumulation and reinvestment that continues today: profits are not extracted for lifestyle but redeployed into higher-value inventory, larger cash reserves, and strategic infrastructure like the Cotswolds showroom — described by the director as circa 60,000 sq ft, though architectural plans specify approximately 42,500 sq ft — self-funded with no external finance required. The showroom officially opened on 29 June 2026, with facilities including a photography studio, client lounge, detailing facilities, and landscaped grounds.
Visual Data Benchmarking: Tom Hartley Jnr Limited Key Financial Performance Indicators
| Metric | Value | Operational Impact | Status |
|---|---|---|---|
| Direct Corporate Turnover | £181M+ (FY2023); £173.29M (FY2025) | Baseline stock revenue from owned inventory sales | Verified via Companies House Registry |
| Total Concluded Volume | £200M+ | Includes off-market commission brokerage and private treaty sales | Verified via Director Statement |
| Net Corporate Profit | £20.1M (FY2023); £32.33M (FY2025) | FY2023 profit: £20.1M; FY2025 profit: £32.33M (342% increase on FY2024’s £7.31M) | Verified via Companies House Filings |
| Physical Stock Allocation | £72M | Risk-bearing high-value hypercar and classic Ferrari inventory | Verified via Balance Sheet Disclosure |
| Cash Reserves | £32M+ (£32.59M FY2025) | Immediate purchasing liquidity buffer; zero external debt | Verified via Companies House Accounts |
Next Filing Dates: Accounts to 31 March 2026 due by 31 December 2026. Next confirmation statement date: 3 May 2027, due by 17 May 2027. Last confirmation statement filed: 3 May 2026. — Verify on Companies House
Source Verification Key
🟢 Statutory Filings: Data pulled from audited or director-signed accounts submitted to Companies House. These are legal documents.
🟡 Director Statement: Information sourced from official press releases, interviews, or company website claims that haven’t yet appeared in a statutory filing.
The 2026 Competitive Edge: Market Knowledge and Off-Market Ecosystem
Business Model Analysis
Two Revenue Engines: How Tom Hartley Jnr Generates Income
The business runs two parallel revenue models simultaneously — one capital-intensive, one relationship-intensive.
| Factor | ⬤ Principal Trading (Owned Stock) | ◯ Commission Brokerage (Off-Market) |
|---|---|---|
| Capital at Risk | Full purchase price of each vehicle — up to £41M+ per asset for a 1962 Ferrari 250 GTO | Zero — no corporate capital deployed; deals run on relationship and expertise alone |
| Margin Profile | 13.5%–18.5% gross — verified via Companies House statutory accounts | Commission percentage — undisclosed publicly; structurally high-margin given zero capital outlay |
| Notable Examples | 1962 Ferrari 250 GTO · 1965 Ferrari 275 GTB · McLaren P1 · Porsche 918 Spyder · McLaren F1 | Ecclestone 69-car F1 collection (~£500M) · Ojjeh McLaren collection (20 cars, 8-figure sum) |
| Revenue Visibility | Appears in full as turnover in statutory Companies House accounts | May appear in accounts as commission income or blended within turnover — not always separately itemised |
| Key Risk | Capital locked in illiquid assets — a misjudged acquisition can tie up millions with no short-term exit path | Entirely relationship-dependent — deal flow exists only as long as client trust and market reputation are maintained |
Margin data sourced from Companies House statutory accounts (06712857). Deal values from Car Dealer Magazine and press reporting.
Last Updated: FY2025The true valuation multiplier of the Hartley Jnr brand cannot be captured in balance sheet line items alone. In a market where a single asset can fluctuate by millions based on provenance, condition, and buyer sentiment, his ability to conclude more than £200 million in total transactional volume—including off-market brokerage—hinges entirely on a non-replicable individual expertise that has been compounding since age 11.
This ‘gut-feeling’ is an accumulated knowledge base built from 25 years of tracking the provenance and auction performance of specific chassis numbers. When Hartley Jnr states that “the director’s market knowledge on the particular cars and gut feeling of the market is very important”, he is describing an intangible asset that no competitor can acquire through hiring or technology. In the classic car ecosystem, where RM Sotheby’s can sell a 1962 Ferrari 330LM/250 GTO for close to £41 million, the spread between informed and uninformed pricing can run into eight figures. Hartley Jnr’s margin expansion from 13.5% to 18.5% reflects the ability to source, price, and exit positions with increasing precision — a skill that improves with every transaction.
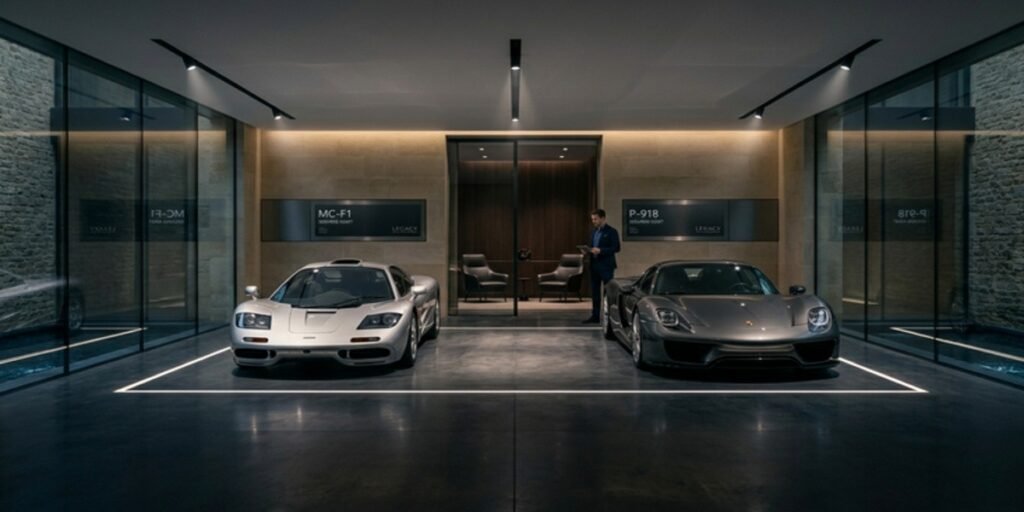
The off-market ecosystem represents a parallel revenue channel of equal significance. Private commission brokerage from unlisted hypercars generates zero-inventory, high-margin revenue streams that bypass typical capital depreciation risks entirely. When Hartley Jnr brokered the Ecclestone collection sale or the Ojjeh McLaren collection, he deployed relationship capital rather than balance sheet capital—earning commission percentages on transactions where he bore no inventory risk. The calibre of Hartley Jnr’s client network is reflected in public testimonials: Adrian Newey OBE — the legendary F1 car designer, formerly Chief Technical Officer at Red Bull Racing and now Managing Technical Partner at Aston Martin — is among named clients who have purchased through the dealership. The Ojjeh collection sale was agreed in August 2025 to a single anonymous buyer who purchased the entire 20-car ensemble intact, with the proceeds expected to appear in FY2026 accounts. These deals contributed to the 2025 margin expansion to 18.5%, which Hartley Jnr explicitly attributed to “the number of sales concluded on a consignment basis”.
This dual-revenue architecture—owned inventory generating 13.5%+ margins on capital at risk, plus commission brokerage generating high-margin fees on zero capital at risk—creates a resilient personal cash flow channel that insulates Hartley Jnr’s wealth from inventory market corrections. It is the same structure employed by elite art dealers and prime real estate brokers, but executed in an asset class where Hartley Jnr holds a documented 25-year track record and a controlling position in some of the market’s most significant transactions.
For context, Spear’s Magazine has described Tom Hartley Jnr as one of very few dealers at this level to own the stock it sells — a model that distinguishes the business from pure-brokerage competitors in the ultra-luxury market.
Frequently Asked Questions: Corporate & Financial Audit
What is Tom Hartley Jnr’s verified business revenue?
According to official documents filed at the UK Companies House Registry, Tom Hartley Jnr Limited reported an audited turnover of £181 million for the financial year ending March 2023, and £173.29 million for the fiscal year ending March 2025. However, the director has confirmed that total concluded transaction volume was well over £200 million when accounting for private, off-market commission brokerage channels. No verified personal net worth figure exists as of 2026.
How much profit does his company make per year?
The company’s statutory filings reveal a pre-tax profit of £32.33 million for FY2025, a 342% increase from the £7.31 million recorded in FY2024. This trajectory builds on a historical profit baseline of £20.16 million generated in FY2023. The corporate entity distributed £7 million in ordinary dividends during the 2025 financial period, with Tom Hartley Jnr receiving the majority share as controlling stockholder.
Does Tom Hartley Jnr hold his own stock or sell on commission?
Both models are utilized. The core corporate strategy focuses on the outright cash purchase of high-value assets rather than standard consignment brokering, allowing the business to capture larger market spreads by assuming full inventory risk. However, the firm simultaneously executes high-margin, off-market commission sales. The FY2025 margin expansion was attributed by the director to “the number of sales concluded on a consignment basis,” with the Ecclestone collection sale completing around the March 2025 year-end. The subsequent Ojjeh McLaren collection sale is expected to contribute to FY2026 accounts — a deal with the collection estimated at £300 million to £500 million by British media, though the actual sale price remains undisclosed.
What is the debt risk profile of the business infrastructure?
The risk profile is exceptionally low compared to traditional premium automotive groups. Balance sheet audits demonstrate zero outstanding debt liabilities, commercial charges, or active property mortgages against the company. Operational expansion—including the development of their landmark showroom facility in the Cotswolds — described by the director as circa 60,000 sq ft, though independent architectural filings specify approximately 42,500 sq ft—is self-funded directly out of the firm’s cash allocations, which stood firmly at £32.59 million at the close of the 2025 fiscal period.
Has the business expanded beyond car sales?
Yes. Tom Hartley Jnr Storage Ltd (company number 17023602) was incorporated on 10 February 2026 at the same registered address as the main trading company. The storage facility is located adjacent to the new Cotswolds showroom in Hook Norton, Oxfordshire, and offers appointment-only, climate-controlled car storage for collectors — extending the business model beyond acquisition and sale into ongoing asset custody.