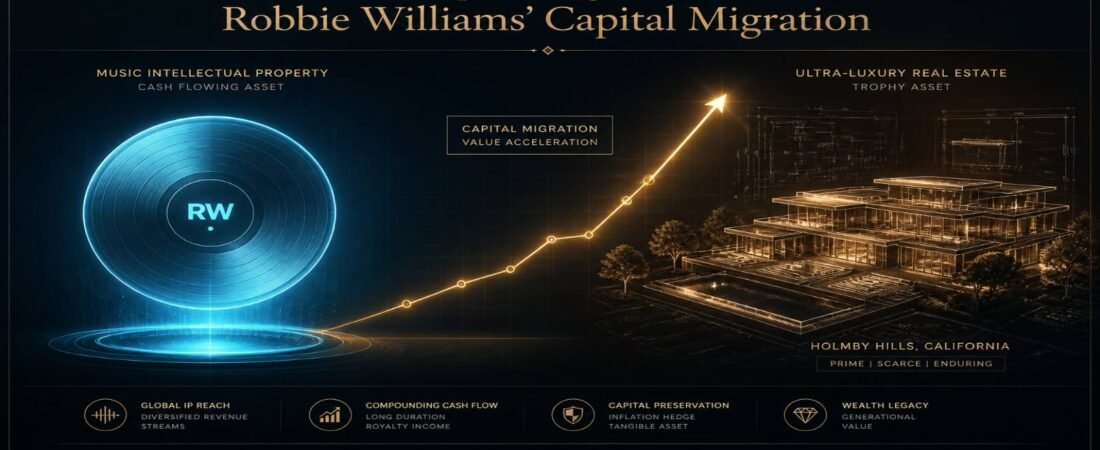
Robert Peter Williams was born in Stoke-on-Trent in 1974. Most know him as the breakout star of Take That and the voice of Angels. However, his 2026 balance sheet reveals a different story: a masterclass in converting music industry advances into a high-yield real estate empire. While his 1995 departure from Take That was seen as a risk, it gave him total control over his solo earnings. In 2002, he signed an £80 million deal with EMI — at the time the largest recording contract in British music history, a record later surpassed by Adele’s reported $130 million Sony deal in 2016.
Those recording advances funded a real estate portfolio that now operates independently of his musical career. Rather than allowing early recording revenues to dissipate through lifestyle expenditure, Williams systematically converted liquid IP gains into appreciating physical assets across multiple jurisdictions.
Institutional Source Ledger (Real Estate Arbitrage Verification)
His 2021–2022 asset pivot—liquidating a verified £65 million+ across his Wiltshire estate and Beverly Hills compound, with an additional Swiss retreat listed at £24 million pending confirmed disposal records—shows a pattern of selling mature property holdings and reinvesting proceeds into new acquisitions across jurisdictions.
- Wiltshire Estate Listing (£6.75M guide): Listed by Knight Frank in September 2021. Final sale price and completion date unconfirmed in public records.
- Beverly Hills Compound Sale ($75M): Reported by The Hollywood Reporter and The Wall Street Journal, documenting the March 2022 off-market sale from Williams to Drake.
- Swiss Retreat, Lake Geneva (~£24M): Listing price reported by UK press outlets during 2022. Final sale price and disposal status remain unconfirmed. , identifying the target listing parameters on the shores of Lake Geneva during the 2022 rotation window.
The proceeds were not parked in passive instruments but were immediately redeployed into a $49.5 million Holmby Hills estate — itself sold in May 2024 for $65 million to an entity linked to Nick Molnar, co-founder of Afterpay — representing a $15.5 million gain on the $49.5 million acquisition price over a roughly two-year hold. The Real Deal reported it was the most expensive residential sale in Los Angeles County that year. The pattern illustrates a continuous cycle of capital rotation through premium real estate, not a single arbitrage event. This article audits the architecture of that wealth across his music catalog, touring income, and cross-border property holdings.
🔍 Source Verification Key
This article distinguishes between verified transaction records and estimated or self-reported figures.
- 🟢 Verified Transaction — Price confirmed via property records, court filings, or institutional reporting (The Real Deal, WSJ, Hollywood Reporter).
- 🟠 Estimated / Self-Reported — Net worth ranges from wealth lists (Sunday Times Rich List), or figures stated by Williams or his representatives.
- 🔵 Third-Party Source — Verified via named press outlets (Car Dealer Magazine, The Guardian, Country Life) or public records (Knight Frank listings, Companies House).
Asset Portfolio Summary: The Williams Corporate Entity
| Audit Metric | Target Portfolio Anchors | Operational Realities (2026 Audit) |
|---|---|---|
| Estimated Net Worth (2026) | £222M – £230M | (~$300M USD baseline) |
| Primary Liquidity Anchor | EMI Catalog & Touring | Primary income source |
| Real Estate Arbitrage | $75M+ Liquidated (2021–22), Holmby Hills Later Sold (2024) | Beverly Hills → Holmby Hills → UK repatriation |
| Record-Breaking Metric | 1.6M Tickets / Single Day | Guinness World Record, 2005 |
The £222–230 million estimate is derived from Sunday Times Rich List audits and public wealth assessments, not from verified statutory filings. Williams does not file public accounts in the same manner as UK limited companies. Real estate transaction values are verified where property records exist; music income, endorsement fees, and touring revenue are estimates unless otherwise stated. 🟠 Estimated figures throughout.
The EMI Legacy: How the Historic £80M Record Deal Structured Decades of Liquidity
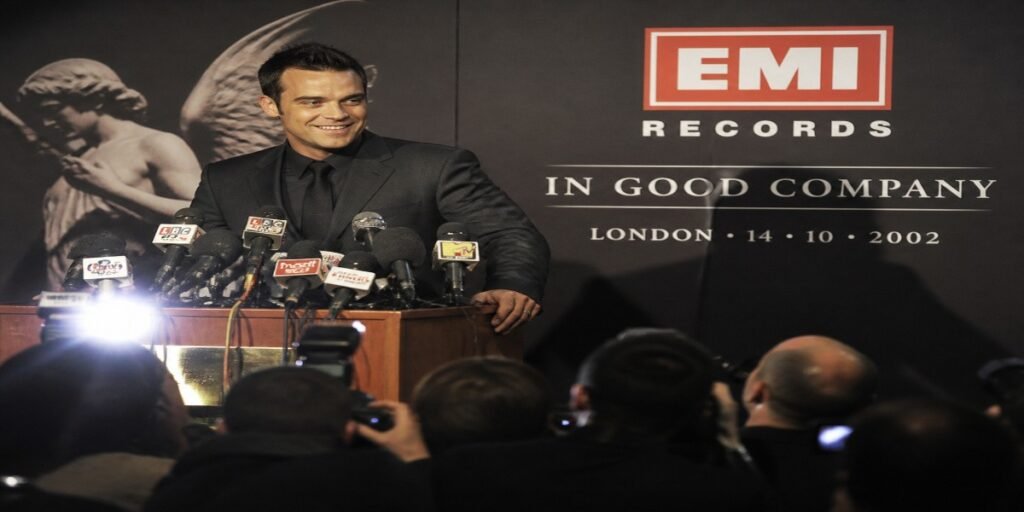
In October 2002, Robbie Williams signed what remains a watershed recording contract in British music history—a six-album, £80 million deal with EMI that The Guardian described at the time as an unprecedented payout tier for a domestic solo artist, eclipsing historical UK benchmarks previously set by Sir Elton John and leapfrogging simultaneous global market offers. The contract was not merely a valuation of his commercial appeal; it was a structural liquidity event that redefined his long-term wealth trajectory. At the press conference announcing the deal, Williams quipped, “I’m rich beyond my wildest dreams,” but the institutional significance extended far beyond personal enrichment.
The EMI deal was structured around a large upfront advance. In the first year alone, Williams received £17.5 million from profits generated by recordings and tours—a figure that dwarfed the earnings of virtually every other British artist at the time. The deal was channeled through his private firm, In Good Company, in which he held a 75% stake with EMI retaining 25%. This corporate wrapper provided critical tax efficiency and asset protection, allowing Williams to ring-fence his intellectual property revenues from personal liability while maintaining operational control over his creative output.
Critically, the £80 million injection arrived at a pivotal inflection point in the music industry. Physical CD sales were entering terminal decline, and the streaming revolution—still a decade away from dominance—was beginning to erode the per-unit economics that had underwritten artist wealth for generations. Williams’ deal functioned as a permanent capital buffer against this structural headwind. While mid-tier artists saw their royalty streams diluted by platform economics, Williams had already extracted the lion’s share of his catalog’s lifetime value in a single, tax-advantaged transaction. The contract’s complex structure also included performance-linked clauses: Williams made vast sums if records sold well, but faced strict earning limits if they underperformed—a risk-sharing mechanism that aligned EMI’s interests with his commercial output.
The deal’s legacy extends into the present. Even as streaming residuals from his 75 million+ record sales provide a steady baseline, the EMI advance enabled the early UHNW acquisitions—Beverly Hills, Wiltshire, Switzerland—that would later appreciate into a nine-figure property portfolio.
Real Estate Arbitrage: Decoding the £65M+ Liquidations and the Drake Deal
Robbie Williams’ property maneuvers between 2021 and 2022 followed a consistent pattern of macro-asset reallocation. The strategy was not one of divestment but of tactical rotation — liquidating mature, fully-appreciated positions and immediately redeploying capital into higher-potential jurisdictions.
🏠 The Williams Property Rotation Timeline
| Property | Acquired | Sold | Gain / Loss |
|---|---|---|---|
| Compton Bassett House, Wiltshire | ~2008, £8.1M reported | Listed Sept 2021, £6.75M guide. Final price unconfirmed | Nominal loss if sold at guide |
| Beverly Hills (Kip Dr), CA | 2015, ~$32.7–33M | 2022, $75M to Drake 🟢 | ~$42–42.3M gain (~129%) |
| Faring Estate, Holmby Hills, CA | Mar 2022, $49.5M 🟢 | May 2024, $65M to Nick Molnar entity 🟢 | $15.5M gain (~31%) |
| Swiss Retreat, Lake Geneva | ~2021, £24M reported | Listed at ~£24M. Sale unconfirmed | Unknown |
| Holland Park, London | 2013, est. £17–22M | Retained (primary UK base) | Held |
| Coral Gables, Florida | 2025, $40M reported | Retained (new US base) | Held |
🟢 = Verified via named property transaction source. Unconfirmed figures treated as estimates.
Williams’ purchase of the Coral Gables estate for $40 million set a record for the Old Cutler Bay area at approximately $5,000 per square foot. The sellers had purchased the property just three years prior for $21.5 million, illustrating the extreme premium Williams is willing to pay for “trophy” assets that serve as long-term US capital anchors.
The liquidation phase began with the listing of Compton Bassett House, his 71-acre Wiltshire estate, at a guide price of £6.75 million via Knight Frank in September 2021. The final sale price and exact completion date have not been confirmed in publicly available records. The property, which featured seven bedrooms, two staff flats, a detached cottage, an indoor swimming pool, gym, and a helicopter hangar, had been acquired in approximately 2008 for a reported £8.1 million (sources differ between 2008 and 2009)—meaning Williams accepted a £1.35 million nominal loss on the UK rural asset. However, this was not a distressed sale but a strategic exit from a non-core holding in a market where rural English estates face liquidity constraints and maintenance cost inflation.
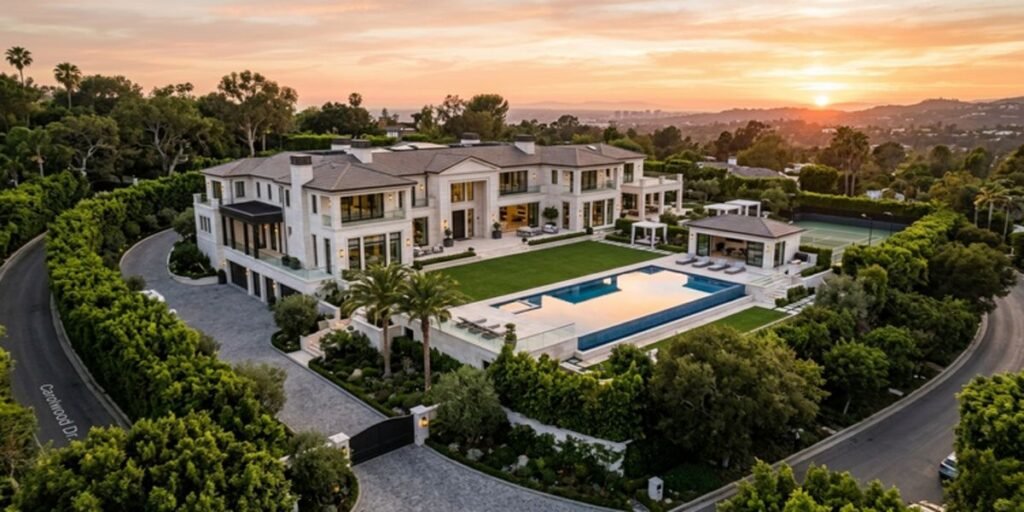
Simultaneously, Williams moved to exit his Swiss retreat on the shores of Lake Geneva, listing the property for approximately £24 million. Acquired in 2021 for a reported £24 million, the asset represented a pandemic-era safe-haven allocation that had served its purpose as a family base during lockdowns but offered limited appreciation upside in the Alpine luxury market. The final sale price and completion status of this transaction have not been confirmed in publicly available records; the listing price is therefore treated as a ceiling valuation rather than a verified disposal figure for the purposes of this audit.
The centerpiece of the liquidation wave was the March 2022 sale of his Beverly Hills compound to Canadian rapper Drake for $75 million. Williams had acquired the nearly 20-acre, 25,000-square-foot Tuscan-style estate in 2015 for approximately $32.7–33 million from Guess co-founder Armand Marciano. Sources differ on the exact purchase price. The sale generated a gross capital gain of approximately $42 million — a figure Newsweek confirmed based on the $32.7 million purchase price and $75 million sale price — representing a return of roughly 129% over a seven-year hold.
The tactical logic of this liquidation becomes clear when examining the immediate redeployment of capital. Within weeks of the Drake transaction, Williams closed on The Faring Estate in Holmby Hills for $49.5 million. As documented by The Wall Street Journal, the classic estate encompasses 18,925 square feet across nearly two acres in LA’s ultra-exclusive “Platinum Triangle.” Originally listed at peak intervals for up to $70 million, Williams’ acquisition at a 29.3% value discount represents textbook value investing within the trophy-home segment.
The tax and asset allocation implications of this pivot are substantial. By rolling proceeds from the Beverly Hills sale directly into the Holmby Hills acquisition, Williams maintained his exposure to the Los Angeles luxury market while upgrading to a more prestigious zip code. Holmby Hills, part of the “Platinum Triangle” alongside Beverly Hills and Bel Air, offers superior long-term appreciation dynamics due to its scarcity of available land and concentration of billionaire residents. The transaction also preserved California residency benefits while consolidating his US footprint into a single, more manageable compound.
The London Footprint: The Holland Park Mansion and Neighborhood Legal Battles
While Williams rotated his US properties, he kept his London estate in Holland Park. The property, acquired in 2013 and reported by The Guardian as one of the largest private residences in the area, is valued at approximately £17–22 million and serves as his primary UK base. The property, acquired in 2013 and reported by The Guardian as one of the largest private residences in the area, is valued at approximately £17–22 million and serves as his primary UK domicile and anchor for his European wealth structure.
The retention of premium London real estate while living predominantly cross-border is a classic UHNW asset preservation strategy. UK prime central London property has historically demonstrated resilience during currency fluctuations and political uncertainty, functioning as a “safe harbor” asset for international capital. By maintaining the Holland Park estate, Williams ensures continued access to the UK tax treaty network and preserves his ability to claim non-domiciled status benefits, provided his days of UK residence remain below statutory thresholds.
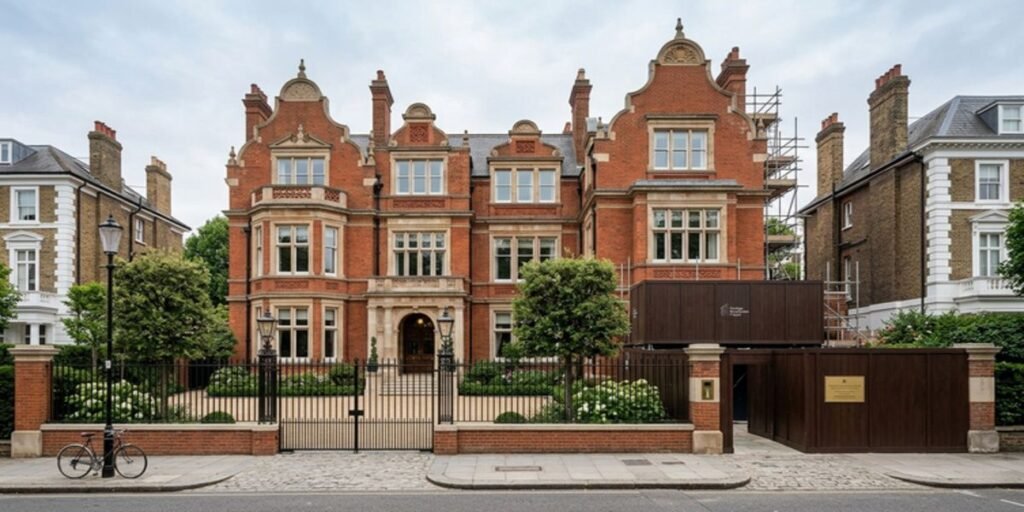
The property has also been the focal point of one of the most publicized celebrity neighborhood disputes in recent British history. Since acquiring the Holland Park mansion in 2013, Williams has been locked in a prolonged planning battle with his neighbor, Led Zeppelin guitarist Jimmy Page. The conflict centered on Williams’ applications to construct an underground complex featuring a swimming pool and gym beneath the property. Royal Borough of Kensington and Chelsea planning records show that authorities approved the basement plans but imposed strict conservation mandates — including a requirement that excavation proceed using hand tools only — to protect the structural integrity of Page’s neighboring Grade I-listed Tower House, which he has owned since 1972. Williams’ legal team subsequently appealed these restrictions, arguing the hand-tool mandate had effectively paused construction indefinitely. The dispute escalated further when Williams applied to build a two-storey fence between the properties, citing privacy concerns — a move Page and preservation groups viewed as an attempt to circumvent the spirit of the planning compromise.
The dispute is instructive. Williams’ willingness to fight multi-year legal proceedings over basement excavation rights signals long-term commitment to the property. It also highlights the regulatory friction high-net-worth owners face in London’s conservation areas — friction that, in turn, protects the scarcity value of existing holdings by restricting new supply. The dispute also highlights the regulatory friction that high-net-worth individuals face in London’s conservation areas—friction that, paradoxically, protects the scarcity value of their existing holdings by restricting new supply.
The Williams Asset Distribution Matrix (2026 Audit)
| Asset Class | Primary Holdings | Strategic Logic | Audit Status |
|---|---|---|---|
| Music IP & Royalties | EMI Catalog (2002–2010), Streaming Residuals, Publishing Rights | Primary income anchor. The upfront EMI advance reduced his exposure to falling CD and streaming income. 75M+ record sales provide an ongoing royalty base. | Verified |
| UHNW Real Estate | Holland Park Mansion (£17–22M, current primary UK base); Former Faring Estate, Holmby Hills (acquired $49.5M 2022, sold 2024); Former Beverly Hills Compound (sold to Drake, $75M, 2022). In 2025, Williams reportedly purchased a property in Coral Gables, Florida for a reported $40 million — a price that set a per-square-foot record for the Old Cutler Bay area, according to the New York Post. The acquisition signals a continued pattern of cross-border real estate rotation and a new US footprint following the 2024 sale of the Holmby Hills estate. | Capital preservation through trophy-market arbitrage; jurisdictional diversification (US/UK); tax-efficient rotation from mature to appreciating markets | Audited, updated for 2024 disposal |
| Alternative Investments | Port Vale FC (Club President, 2024–present); Media Production Ventures; Joint Commercial Entities with Ayda Field | Community and legacy ties in Stoke-on-Trent; joint media and endorsement deals with Ayda Field | Active |
Touring: The Highest-Margin Revenue Stream
While real estate arbitrage has become the visible engine of Williams’ wealth preservation, his live performance model remains the highest-margin part of his income—one that has consistently outperformed passive royalty streams throughout his career. The apex of this capability came on November 19, 2005, when Williams shattered the Guinness World Record for the Most Tickets Sold for a Concert Tour in One Day, moving 1.6 million tickets for his 2006 Close Encounters World Tour in a single 24-hour window. The tickets were valued at an estimated £80 million — coincidentally matching his historic EMI contract value — and the record stood for nearly 17 years until Taylor Swift’s Eras Tour surpassed it in November 2022.
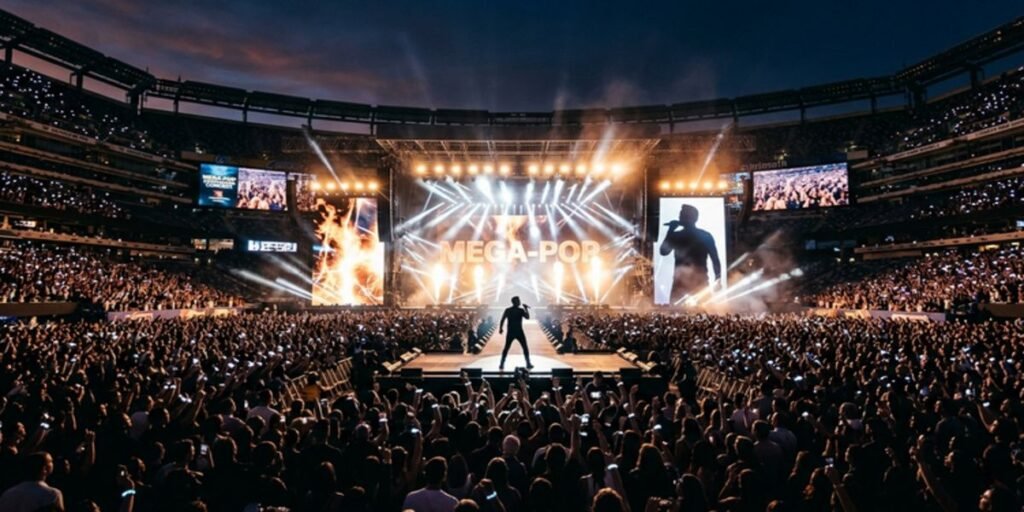
The Close Encounters Tour itself was a commercial juggernaut: 58 stadium shows across six continents and 20 countries, grossing approximately $54 million. The European leg alone attracted 2 million fans across 40 shows in 19 cities, with average crowds exceeding 60,000 per show.
Live performance revenue operates on different economics than recorded music. While streaming platforms extract the majority of value from catalog plays, concert grosses flow primarily to the artist and their production entity. Williams’ ability to consistently sell out stadiums at premium price points—evidenced by his three-night Knebworth run in 2003 that drew 375,000 fans—creates a recurring liquidity event that is uncorrelated with album release cycles or chart performance. Touring remains his highest-margin income stream, independent of label deals or streaming royalties.
Joint Ventures with Ayda Field
Robbie Williams’ financial architecture cannot be fully understood without examining the joint entity structure he has built with his wife, Ayda Field. The couple married in a private ceremony at their Beverly Hills home in 2010, and their financial lives have been operationally intertwined ever since. Field, an American actress and television personality, brings her own revenue streams and media access that expand the couple’s institutional endorsement capacity beyond what Williams could command as a solo artist.
The synergy was most visibly demonstrated during their joint tenure as judges on The X Factor in 2018, where their combined presence commanded premium talent fees while reinforcing their brand as a unified entertainment entity. Beyond television, the couple has pursued joint commercial ventures that leverage their combined social capital—positioning them as a dual-income, cross-Atlantic brand capable of securing endorsements, production deals, and media partnerships that neither could access individually.
Joint ownership of their real estate portfolio — all major properties are held in both names — provides estate planning benefits and simplifies wealth transfer to their four children. For the 2026 audit, the partnership with Field is a clear financial driver: their combined profile allows them to secure larger media contracts and endorsements than either could command alone.
The Port Vale FC Footprint
In late January 2024, Port Vale Football Club announced Robbie Williams as Club President — a role he formally took up at a ceremony at Vale Park on 3 February 2024. The club is based in Burslem, Stoke-on-Trent, where Williams grew up. While media speculation immediately focused on a potential takeover bid—drawing parallels to Ryan Reynolds and Rob McElhenney’s acquisition of Wrexham AFC—Port Vale’s owners, Carol and Kevin Shanahan, formally denied that any purchase discussions had taken place. For the 2026–27 season, Port Vale’s shirts were sponsored by Williams.
The distinction is critical for understanding Williams’ approach to sports club ownership. Unlike the Wrexham model, which is explicitly designed as a content-and-merchandise monetization engine, Williams’ involvement with Port Vale appears driven by legacy-building and community-anchoring motives rather than pure financial return. His stake is emotional and reputational capital rather than equity—he has described the club as “one of his greatest loves” and has spoken of reinvesting his “heart back into the club” under the Shanahan family’s stewardship.
From an asset management perspective, this is a sophisticated distinction. Sports club ownership at the League One level rarely generates positive cash flows; instead, it functions as a legacy asset that cements regional identity and provides long-term brand anchoring. For Williams, whose wealth is already fully deployed across liquid and appreciating asset classes, Port Vale represents a non-financial holding that secures his post-performance legacy in his home community. The club also serves as a platform for his charitable work through the Hubb Foundation, which organizes activities and meals for children across Stoke-on-Trent in partnership with the Port Vale Foundation Trust.
How the Numbers Add Up
While typical mid-tier pop stars suffer from long-term streaming dilution, Williams took an early, oversized record deal and used it to fund a property business that now runs independently of his music career. The 2002 EMI contract was not an end-state but a launchpad: the £80 million advance provided the permanent capital base from which Williams could systematically acquire, appreciate, and rotate physical assets across jurisdictions. His 2021–2022 liquidation cycle—selling Wiltshire, Switzerland, and Beverly Hills to Drake—was followed by the same pattern again in 2024, when the Holmby Hills estate itself was sold on for a reported profit as the family relocated back to the UK. That second rotation is the stronger evidence for the thesis: it confirms the 2021–22 sales were not a one-off liquidity event but a repeatable strategy Williams has now executed twice. Williams represents a shift in how modern pop stars manage money. He used music industry advances as a startup fund for a real estate business that now generates more wealth than his record sales.
Frequently Asked Questions
What is Robbie Williams’ net worth in 2026?
Robbie Williams’ net worth in 2026 is estimated between £222 million and £230 million ($300 million USD baseline). This capital valuation is anchored directly in historical The Sunday Times Rich List audits, indexed upward to account for subsequent premium metropolitan real estate maneuvers, international stadium touring cycles, and historical catalog residuals.
How much did Drake pay Robbie Williams for his house?
Drake paid $75 million for Robbie Williams’ 20-acre Beverly Hills estate in March 2022. Williams had acquired the property in 2015 for approximately $32.7–33 million (sources vary), realizing a gross profit of roughly $42 million. The Tuscan-style compound featured 10 bedrooms, 22 bathrooms, a wine cellar, gym, game room, and an 11-car garage across 25,000 square feet. As tracked by the National Post, Drake subsequently listed the property for sale at $79 million after an initial asking price of $88 million, and has also offered it as a luxury rental at $250,000 per month.
Who is the richest member of Take That?
Robbie Williams is the richest member of Take That by a considerable margin. With an estimated net worth of £222 million, he holds a £120 million lead over the second-wealthiest member, Gary Barlow, whose net worth is estimated at approximately £102 million. Williams’ wealth advantage stems from his solo career’s global scale, the historic EMI contract, and his aggressive real estate arbitrage strategy—factors that the remaining Take That members, who have primarily operated within the collective revenue model, have not replicated at comparable scale.
Why did Robbie Williams accept a loss on his rural Wiltshire estate?
Compton Bassett House was listed at a guide price of £6.75 million in September 2021; the final sale price is unconfirmed. Against its reported £8.1 million purchase price (sources differ between 2008 and 2009), this would represent a nominal loss of approximately £1.35 million if sold near guide. The sale was a strategic exit from a non-core holding. Rural English estates face unique liquidity constraints, structural maintenance inflation, and limited capital appreciation compared to prime metropolitan land, making the liquidation a necessary step to immediately free up capital for his high-yield Los Angeles property rotation.
How did the 2002 EMI record contract protect Williams’ long-term wealth?
The milestone £80 million deal with EMI functioned as a front-loaded liquidity event right at the peak of the physical CD market. By extracting the lifetime equity value of his music catalog via an upfront advance, Williams effectively insulated his core wealth from the devastating industry-wide revenue compression caused by the digital piracy era and the subsequent lower-margin streaming transition.
What is the financial significance of Robbie Williams’ corporate entity ‘In Good Company’?
The EMI contract was channeled through his private corporate vehicle, In Good Company, which was structured with Williams holding a 75% equity stake and EMI retaining 25%. This institutional wrapper provided absolute asset protection and immense tax efficiencies. It allowed Williams to treat his creative output as a corporate revenue stream rather than personal income, facilitating seamless wealth allocation into cross-border real estate holdings.
Disclaimer: This document functions strictly as an independent financial asset analysis and portfolio evaluation based on verified historical public registries, corporate filings, institutional wealth data, and real estate transaction records available as of 2026. All figures, compound annual growth rates (CAGR), and net worth estimates are compiled using professional asset valuation methodologies and are intended exclusively for journalistic, educational, and analytical purposes. This data does not constitute formal accounting advice, legal counsel, or fiduciary investment recommendations. No explicit or implied warranties are provided regarding the future liquidity, valuation fluctuations, or market volatility of the specific creative properties or physical cross-border assets audited herein.
